Somalia Restores IATA’s BSP After 35 Years as Travel Trade Seeks Direct Access to Global Airlines

Somalia has formally relaunched the International Air Transport Association’s Billing and Settlement Plan (BSP) after a 35-year absence, restoring a central system for processing airline ticket sales and payments as the country works to rebuild its aviation industry.
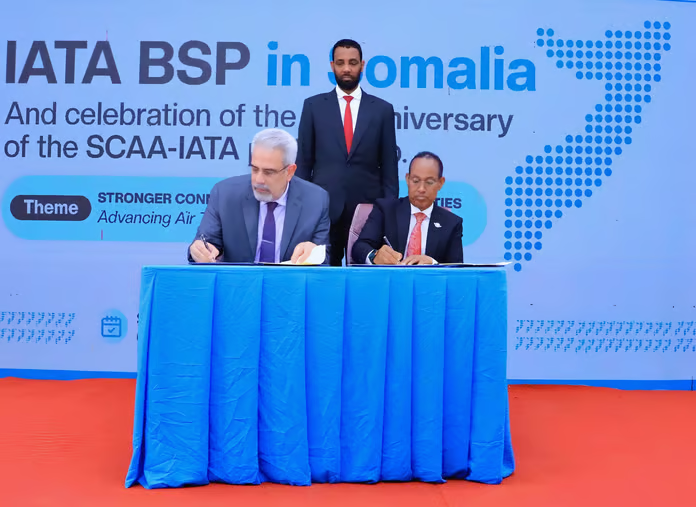
The relaunch, held in Mogadishu on October 18, 2026, was attended by Prime Minister Hamza Abdi Barre and senior aviation officials. It coincided with an agreement recognising IATA’s international safety audit programmes for airlines and ground-handling companies, marking two developments in the country’s efforts to strengthen its aviation infrastructure and regulatory framework.

For Somalia’s travel trade, the return of BSP provides a mechanism through which IATA-accredited travel agents can report ticket sales and settle payments with participating airlines through a centralised system rather than managing separate settlement arrangements with individual carriers.

The system could reduce administrative work, improve reconciliation of ticket revenues and give airlines greater visibility over sales and payments in the Somali market. Its commercial value will depend on participation by airlines and accredited agencies, as well as the financial and operational arrangements supporting its implementation.

IATA announced a pilot programme on April 30, 2026, involving four travel agencies and several airlines serving Somalia, including Ethiopian Airlines. At the time, the association said it intended to open the system more widely, targeting more than 300 travel agents operating in the country.

The October relaunch marks the formal return of the settlement system after decades without a domestic BSP arrangement. However, the number of agencies and airlines actively participating following the relaunch has not been publicly confirmed.

A US$242 billion global settlement system

The scale of IATA’s global settlement operations illustrates the importance of the infrastructure being restored in Somalia.

In 2025, BSP processed more than 700 million transactions across over 180 countries, with a total value of US$242 billion, according to IATA. The system serves hundreds of airlines and tens of thousands of travel agents worldwide.

BSP consolidates ticket sales reporting and payments, allowing agents to submit sales information through a central mechanism from which payments are distributed to participating airlines. It also supports the administration of refunds, billing adjustments and other ticketing-related transactions.

For travel agencies, the arrangement can simplify financial reconciliation and reduce the administrative burden of dealing separately with multiple carriers. For airlines, it provides a standardised framework for collecting ticket revenue and monitoring sales through accredited distribution partners.

The system does not eliminate the need for financial controls or guarantee access to every airline. Participation, accreditation requirements and applicable settlement rules remain important conditions for agencies seeking to use it.

Somalia’s reinstatement also has implications for the relationship between local travel businesses and international carriers. IATA has identified the country’s diaspora and expanding trade links across Africa and the Middle East as factors supporting demand for air travel.

A more structured settlement framework could make it easier for participating airlines to work with accredited Somali agencies, although the extent of any resulting increase in bookings or airline capacity remains uncertain.

Safety audits recognised under national regulations

The BSP relaunch coincided with a memorandum of understanding signed on October 18 between IATA, Somalia’s Ministry of Transport and Civil Aviation, and the Somali Civil Aviation Authority.

Under the agreement, the regulator will recognise two IATA audit programmes as acceptable means of demonstrating compliance with national regulations: the IATA Operational Safety Audit (IOSA) and the IATA Safety Audit for Ground Operations (ISAGO).

IOSA assesses an airline’s operational management and control systems, while ISAGO examines the management systems and procedures used by ground-handling companies. Its scope includes passenger and baggage handling, aircraft ramp operations, load control, and cargo and mail handling.

The recognition is intended to support the use of internationally established audit standards and reduce duplication in compliance assessments. The programmes will complement, rather than replace, the Somali Civil Aviation Authority’s statutory safety oversight responsibilities.

The agreement was signed by Transport and Civil Aviation Minister Mohamed Farah Nuh, aviation authority director-general Ahmed Moallim Hassan, and IATA regional vice-president for Africa and the Middle East Kamil Alawadhi.

The arrangement forms part of IATA’s Focus Africa initiative, which identifies safety, infrastructure, connectivity, financial services, sustainability and workforce skills among the priorities for improving African aviation.

For airlines and ground-handling operators, acceptance of recognised audits may help streamline aspects of regulatory compliance. Its practical effect will depend on how the Somali regulator applies the agreement and the requirements individual operators must continue to meet.

Rebuilding aviation infrastructure

Somalia’s return to BSP comes amid broader efforts to restore national aviation functions following decades of institutional disruption.

In January 2023, Somalia resumed air traffic control services in high-altitude Class A airspace within the Mogadishu Flight Information Region after approximately three decades of disruption. The recovery involved improvements to aviation communications, navigation infrastructure and operational capacity.

The restoration of settlement services addresses a different part of the aviation system: the financial infrastructure connecting travel agents and airlines. Together with the recognition of international safety audits, it reflects efforts to strengthen the institutions and processes needed to support commercial air transport.

For Somalia’s travel businesses, the immediate priority will be translating the formal relaunch into reliable access to participating airlines, predictable settlement procedures and effective support for accredited agencies.

The BSP return alone does not establish how much additional ticket revenue will be generated, nor does it guarantee that all local agencies will be able to use the system. Those outcomes will depend on participation, implementation and the development of the wider aviation market.

Nevertheless, after 35 years without a domestic BSP arrangement, the relaunch restores an important link between Somalia’s travel trade and the global airline distribution system. The accompanying safety agreement adds a regulatory dimension to the effort, as the country seeks to strengthen both the commercial and operational foundations of its aviation industry.

Source: somalilandstandard.com
Zanzibar Air Capacity Set To Soar 33% As New Tourism Data Reveals Changing Visitor Trends

Zanzibar is set for a significant expansion in air connectivity, with available airline seats forecast to increase by 33% over the next six months, according to new tourism intelligence released by the African Travel and Tourism Association (ATTA) at the international Buyer Forum, Essence of Africa, being held this week in Zanzibar between 20 and 22 October.

Analysis developed using Data Appeal’s Mabrian Travel Intelligence platform reveals strong growth in connectivity, changing international source markets and evolving visitor preferences.

Zanzibar’s inbound air capacity increased by 11% between October 2025 and October 2026, driven by international capacity growth of 11% and a particularly strong 26% increase in long-haul seats.

The momentum is expected to accelerate over the next six months, with domestic capacity forecast to rise 36% and international capacity 31% year-on-year.

The increase is accompanied by stronger forward flight bookings through global distribution systems (GDS), which are up 10% year-on-year for travel through March 2027.

Changing source markets

The Data Appeal’s Almaviva Group analysis highlights significant changes in Zanzibar’s international source markets, with expanding air connections from the Gulf, Europe and Russia.

The United Arab Emirates, Zanzibar’s fourth-largest international market by available flight seats, is forecast to record a 57% increase in inbound capacity over the next six months. Qatar is expected to grow by 17%, while Oman is forecast to more than double its available seats, rising 108%.

The figures reinforce the growing importance of Gulf aviation hubs in connecting Zanzibar with international travellers.

Established European markets also continue to demonstrate strong demand, with forward GDSs flight bookings from the UK increasing 51% year-on-year, followed by Germany (+14%) and France (+8%).

Russia has also recorded a notable increase in travel activity following the introduction of direct Moscow–Zanzibar services in July 2026. GDS flight bookings from Russia for travel through March 2027 have increased 98% year-on-year, while Zanzibar’s share of outbound flight searches from the Russian market has risen by approximately 8 percentage points.

The findings illustrate how Zanzibar’s international visitor markets are evolving as airline networks expand and travel patterns change.

Hotel rates fall despite growing visitor demand

While air connectivity and flight bookings are increasing, Zanzibar’s accommodation market is experiencing a more competitive pricing environment.

The Data Appeal – Almaviva Group analysis reveals that weighted average room rates advertised through online travel agencies fell approximately 18% year-on-year across the 12 months to October 2026, with declines recorded across all hotel categories.

The findings suggest increasing competition within the accommodation sector, potentially influenced by expanding international hotel brands and wider market conditions.

Zanzibar’s online hotel supply remains concentrated in the midscale segment, with 3-star properties accounting for 57%, followed by 4-star hotels at 28% and 5-star properties at 15%.

Beyond the beach: wellness, culture and independent travel gain ground

The Data Appeal’s Almaviva Group analysis also reveals how Zanzibar’s tourism appeal is evolving beyond its traditional sun-and-sea offering.

While beach experiences remain the leading driver of visitor interest, accounting for 23% of tourism-related related to social media mentions, active lifestyle experiences now represent 19%, followed by arts and culture at 16%.

Interest in family activities, wellness and gastronomy has also increased compared with the previous year.

The findings suggest opportunities for tourism businesses to diversify their products and attract visitors seeking experiences beyond the island’s beaches.

The visitor demand profile shows that couples remain Zanzibar’s largest traveller segment, accounting for 46% of reviewers.

Although hotels and resorts continue to account for more than 70% of reviewed stays, alternative accommodation including apartments, hostels and homestays is gradually gaining market share, suggesting growing demand for flexible and independent travel.

Strong destination reputation

Zanzibar continues to enjoy a strong reputation among international travellers, recording a Global Tourist Perception Index of 86 out of 100, supported by particularly high scores for Security (95) and Climate (90).

However, the findings also identify opportunities to strengthen the visitor experience. Zanzibar’s Tourism Product Index stands at 65/100, while its Hospitality Satisfaction Index is 74/100.

Satisfaction varies across accommodation categories, with 3-star properties scoring 69/100, compared with 77/100 for 5-star hotels and resorts.

Virginia Messina, CEO of ATTA, said:

“There’s no doubt, Zanzibar’s excellent reputation as a destination, exceptional natural environment and increasingly diverse visitor offering is driving airlines’ confidence to increase airline seats over the next six months and beyond.

Established European markets remain extremely important, while growing connections through the Gulf and other international gateways are creating opportunities to reach a broader range of travellers.

But growth in airline seats and bookings must also translate into sustainable commercial returns, investment in the visitor experience and benefits for local communities. These findings reinforce the importance of continued investment in hospitality standards, skills and tourism product development as Zanzibar expands its international reach.

“As Zanzibar continues to attract international investment and new hospitality brands, maintaining competitiveness while protecting the quality and value of its tourism product will be essential. The opportunity is to build on the destination’s popularity while encouraging visitors to stay longer, explore more and spend more widely within the local economy.”

Source: atta.travel

Jambojet Explores South Sudan Expansion After Talks with Juba Regulator

Kenyan low-cost carrier Jambojet is exploring entry into South Sudan, opening a potential new market for the airline as it pursues regional expansion beyond its established domestic network.

The airline held talks with the South Sudan Civil Aviation Authority (SSCAA) in Nairobi on October 22, 2026, to discuss the possibility of operating services into the country. The regulator expressed its willingness to work with the carrier, subject to compliance with foreign-operator regulations and applicable safety requirements.

No route, flight frequency or launch date has been announced, and the discussions do not constitute approval to operate.

The talks come as Jambojet develops a longer-term network strategy aimed at expanding its reach beyond Kenya. The airline resumed daily flights between Nairobi and Entebbe on October 1, 2026, after suspending the Uganda service during the Covid-19 pandemic in 2020.

South Sudan would offer another potential regional market, with Nairobi already serving as an important aviation gateway for travel to Juba. Kenya Airways operates the Nairobi–Juba route, meaning any Jambojet entry would place the low-cost carrier in a market already served by an established regional airline.

The commercial opportunity will depend on the route’s passenger demand, operating costs, fares and the regulatory conditions governing market access.

Jambojet’s expansion plans are also tied to its fleet strategy. The airline operates De Havilland Canada Dash 8-400 turboprop aircraft, which are suited to short-haul services. In September 2026, Jambojet chief executive Karanja Ndegwa told Aviation Week that the airline was developing a 10-year network strategy that would inform future fleet and route decisions.

The carrier has previously outlined plans to increase its fleet from 11 aircraft towards 16 by 2029, supporting growth in its existing markets and potential entry into additional regional destinations.

For the travel trade, a Jambojet service to Juba could introduce another option for passengers travelling between Kenya and South Sudan, depending on the route selected and the fares offered. Travel agents, corporate travel managers and tour operators would need confirmed schedules and booking availability before incorporating the service into their products.

The regulatory process remains the immediate hurdle. During the October meeting, the SSCAA discussed its Commercial Air Transport by Foreign Air Operator Regulations, 2026, which govern foreign airlines seeking to provide commercial services in South Sudan. The authority also outlined its traffic-rights framework and invited a Jambojet delegation to Juba for further discussions.

The next steps will therefore involve regulatory engagement and the fulfilment of applicable operational and safety requirements before any service can be confirmed.

For now, South Sudan remains a prospective destination in Jambojet’s regional expansion plans rather than an announced addition to its published network.

Source: NewsAero

Kenya, Tanzania and Uganda’s AFCON Plan Puts Billions in Travel and Tourism Revenue in Focus

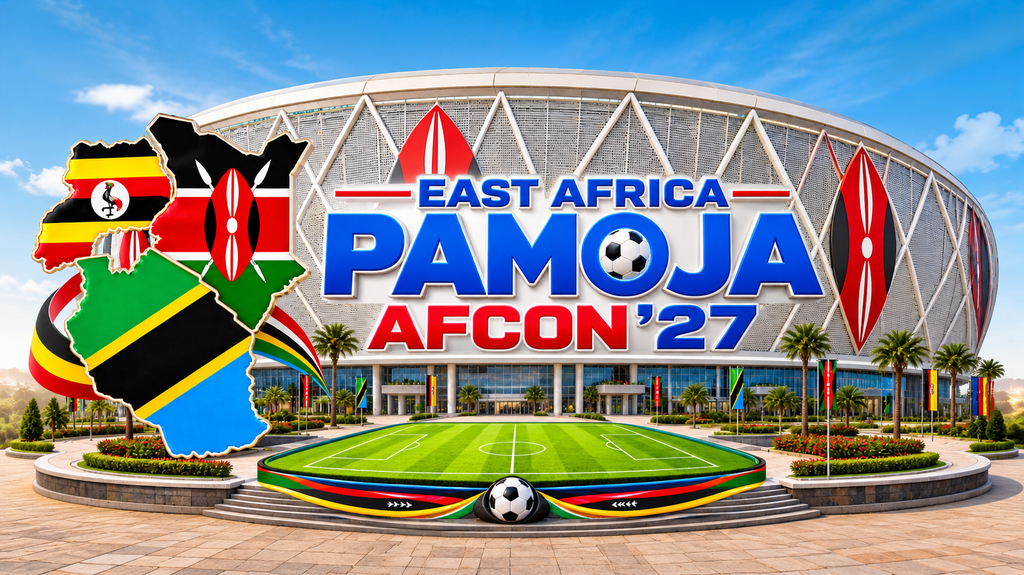
Kenya, Tanzania and Uganda are exploring a common tourist visa for the 2027 Africa Cup of Nations (AFCON), an initiative that could ease cross-border travel and create new business opportunities for airlines, travel agents, hotels and tour operators across East Africa.

The proposal comes as the three countries report rising international visitor numbers and tourism earnings, strengthening the commercial case for marketing them as a connected destination rather than competing national markets.

Combined, Kenya, Tanzania and Uganda recorded approximately 6.63 million international tourist arrivals in 2025, generating about US$9.9 billion in tourism earnings, based on their respective national statistics. The figures cover different national reporting systems and should not be interpreted as a count of unique travellers across the region.

Kenya recorded approximately 2.7 million international arrivals and tourism earnings of about Sh500 billion in 2025. Tanzania received 2.29 million international visitors, generating US$4.41 billion, while Uganda recorded 1.64 million arrivals and tourism receipts of US$1.62 billion.

The proposed visa was endorsed by Ugandan President Yoweri Museveni during a meeting with the country’s AFCON Local Organising Committee in July 2026. The proposal envisages a four-month arrangement allowing eligible football supporters, tourists, officials and participating teams to travel between the three host countries without obtaining separate entry permits for each.

Museveni directed officials to begin discussions with Kenya and Tanzania. However, the endorsement is not a final tripartite agreement, and the proposed visa’s fee, eligibility rules, application process and operational dates have yet to be confirmed.

The timing is significant. AFCON 2027 is scheduled to run from June 19 to July 17, 2027, giving the tournament a defined window around which tourism businesses can develop regional travel products.

Three tourism markets, one regional opportunity

The scale of the three markets offers a useful starting point for assessing the opportunity.

Kenya’s international arrivals increased from approximately 2.47 million in 2024 to 2.7 million in 2025, a rise of about 9 per cent. Tourism earnings increased from Sh452.2 billion to approximately Sh500 billion over the same period.

Tanzania’s international arrivals rose 7.1 per cent, from 2.14 million in 2024 to 2.29 million in 2025. Tourism earnings grew 13 per cent, from US$3.90 billion to US$4.41 billion.

Uganda recorded 1.64 million international arrivals in 2025, up from 1.37 million in 2024, representing growth of approximately 19.7 per cent. Tourism receipts increased to US$1.62 billion from US$1.28 billion in 2024.

These figures point to three substantial tourism economies with complementary products: Kenya’s wildlife and coastal circuits, Tanzania’s safari and Zanzibar markets, and Uganda’s gorilla trekking, wildlife and cultural experiences.

For the travel trade, the commercial question is whether the visa can help turn these separate products into itineraries that generate additional nights, bookings and spending across more than one country.

A visitor attending a match in Nairobi, for example, could extend the trip to a Kenyan safari or the coast before travelling to Tanzania or Uganda. Such an itinerary would create opportunities for travel agents to combine international air tickets, regional flights, accommodation, transfers, park visits and guided excursions into a single sale.

However, these are potential business opportunities, not confirmed projections of additional arrivals or revenue. The actual return will depend on the visa’s final terms, transport connections, accommodation availability and the extent to which visitors choose to travel beyond the tournament venues.

The existing regional visa leaves Tanzania outside the arrangement

East Africa already has a common tourist visa covering Kenya, Uganda and Rwanda. The existing East Africa Tourist Visa costs US$100 and allows eligible visitors multiple entries into the participating countries for 90 days.

Tanzania is not part of that arrangement, making its inclusion in the proposed AFCON framework a significant policy change if the three governments reach an agreement.

The proposed four-month visa should not be confused with the existing 90-day product. Its price, validity and entry conditions remain unconfirmed, and the current visa’s terms cannot automatically be applied to it.

For travel companies, a clearly defined common visa could reduce uncertainty when quoting multi-country holidays. It could also simplify the explanation of entry requirements for international clients, although passport, immigration and other applicable conditions would still need to be observed.

The policy challenge is to ensure that the arrangement works across three national immigration systems without creating confusion over fees, permitted stays, border controls and the treatment of visitors entering or leaving the region more than once.

Regional tourism strategy sets a longer-term ambition

The visa proposal is part of a wider effort to strengthen East Africa’s position in the international tourism market.

On October 15, 2026, tourism ministers from the East African Community adopted a ten-year tourism marketing strategy covering 2027 to 2036. The framework promotes the region as a single destination under the brand Visit East Africa: Feel the Vibe, with priorities including digital marketing, cross-border packages, improved tourism statistics and progress towards a single tourist visa.

The strategy gives the AFCON initiative a longer-term context. If the visa and joint marketing arrangements are implemented effectively, the tournament could help establish regional itineraries that continue to be sold after the final whistle.

The EAC has also urged member states to improve tourism establishment classification ahead of the tournament, highlighting accommodation standards and service quality as important parts of the visitor experience. Uganda is scheduled to host the fourth EAC Regional Tourism Expo alongside the Pearl of Africa Tourism Expo in May 2027, incorporating AFCON promotion and multi-country tourism packages.

For tourism businesses, this creates a potential route from event-driven promotion to sustained regional sales. But marketing a destination jointly will only be commercially effective if travellers can move between countries conveniently and receive consistent service standards.

Visitor spending matters more than arrivals alone

The national earnings figures also show why the opportunity should be assessed in terms of visitor spending, not just the number of football supporters entering the region.

In Tanzania, tourism earnings increased 13 per cent in 2025, faster than the 7.1 per cent rise in international arrivals. The country reported average tourist expenditure of US$289 per person per night on the mainland, while Zanzibar recorded US$274. Uganda reported average tourist expenditure of US$986 per trip in 2025, up from US$933 in 2024, alongside an increase in average length of stay from 8.7 to 8.8 nights.

These figures use different measures and are not directly comparable. They nevertheless illustrate the commercial importance of encouraging visitors to stay longer, purchase additional experiences and distribute their spending among more tourism businesses.

For travel agents, this could favour packages that combine football with established attractions and clearly priced extensions, rather than itineraries built solely around match attendance. The opportunity will also depend on the availability of regional flights, reliable ground transport and accommodation at the right price points.

The three governments will need to publish the visa rules early enough for operators to price and market their products with confidence. Until then, businesses should avoid presenting the proposed visa as an available service or promising clients unrestricted travel across all three countries.

Implementation will determine the economic return

The proposed visa does not, by itself, guarantee an increase in tourism earnings. Its effectiveness will depend on how quickly the governments settle the technical and administrative details and whether the arrangement is integrated with the wider preparations for AFCON.

The private sector will also need reliable information on match schedules, accommodation capacity, transport links, entry conditions and the availability of regional tourism products. Without these, travel businesses may find it difficult to convert international interest in the tournament into confirmed multi-country bookings.

The stakes extend beyond the month-long competition. Kenya, Tanzania and Uganda collectively generated about US$9.9 billion in tourism earnings in 2025, according to their national figures. A more connected regional market could help the three countries sell longer journeys and broaden the distribution of visitor spending, although the size of any additional revenue remains unknown.

For now, the proposed common visa remains a policy initiative rather than an operational travel product. Its significance will ultimately be measured not by the announcement itself, but by whether it makes cross-border travel easier and creates lasting commercial value for East Africa’s tourism industry.

Source: Kenya Joins Tanzania and Uganda in Bold AFCON 2027 Travel Plan to Simplify Cross-Border Tourism – Travel And Tour World

Congo Brazzaville Moves to Drop Visas for Africans, But an ETA Will Still Apply

The Republic of the Congo has moved a significant step closer to opening its borders to fellow Africans, after the cabinet approved a bill on 14 October that would scrap visa requirements for African nationals from 1 January 2027. For the regional travel trade, it is a development worth watching closely, though one that comes with an important caveat attached.

The legislation gives legal shape to a promise made by President Denis Sassou N’Guesso during Africa Day celebrations on 25 May. That announcement placed Brazzaville alongside a growing group of African governments dismantling the visa walls that have long made travel within the continent more complicated than travelling to Europe. It is worth stating plainly that this concerns the Republic of the Congo, with its capital at Brazzaville, and not the neighbouring Democratic Republic of the Congo, a distinction that regularly trips up even experienced consultants.

Cabinet approval, however, is not the finish line. Parliament must still examine and adopt the bill before anything changes at the border. Until that process concludes, the current entry rules remain in force, and agencies should continue advising clients accordingly rather than selling a future that has not yet arrived.

The detail that matters most for day-to-day practice is this: removing the visa does not mean removing the paperwork. According to the official cabinet communiqué, African nationals granted visa exemption would still need to present a form serving as an electronic travel authorisation, or ETA. This is a familiar model now. It mirrors systems operating or being rolled out in Kenya, the United Kingdom and across the European Union, where the visa disappears but a digital pre-clearance step takes its place.

That substitution is deliberate. The Congolese proposal pairs easier movement with measures designed to manage migration flows and guard against cross-border crime, trafficking and migrant smuggling. Governments across the continent are discovering that openness and control are not opposites, provided the right digital tools sit between them.

Preparation for those tools appears to be underway. Congo’s interior ministry website now lists electronic visas and electronic travel authorisation among services under development, and a testing platform showing possible application procedures has been identified. The important word there is testing. The platform’s status, its conditions and whether it reflects final policy all remain unconfirmed by officials. None of it should be treated as booking guidance.

A substantial number of practical questions remain unanswered, and these are precisely the questions African agencies will need resolved before they can advise with confidence. The final cost of the ETA, its processing time, its period of validity and any exemptions have not been published. Nor has a confirmed launch date for the digital services. Whether the new system will genuinely be faster and cheaper than the visa process it replaces is, at this stage, an open question rather than a guarantee.

This is where experience counts. Across the continent, visa-free announcements have sometimes delivered dramatic improvements in access, and sometimes simply shifted the administrative burden from one window to another at comparable cost. The difference lies entirely in the implementing rules, which usually emerge months after the political headline.

For the trade, the sensible posture is attentive patience. Consultants handling business travel into Brazzaville, or building multi-country itineraries through Central Africa, should note the January 2027 target and monitor parliamentary progress, while keeping existing visa advice in place for clients travelling in the meantime.

The wider direction is nonetheless encouraging. Each government that removes a visa barrier makes the continent incrementally easier to sell as a connected region rather than a collection of separate, paperwork-heavy destinations. Over the coming years, that shift will reshape how African itineraries are built, and agencies that track these regulatory changes early will find themselves advising clients while others are still checking old rules.

Source: travelnews. africa – Congo Brazzaville Moves to Drop Visas for Africans, But an ETA Will Still Apply

Dubai Safari Park Reopens as City Enters Winter Tourism Season

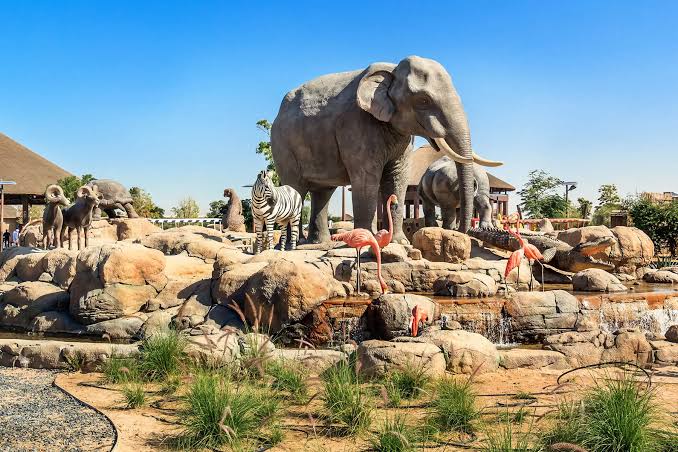
Dubai Safari Park reopened for its eighth season on 12 October, returning to the city’s tourism offering as cooler weather brings more opportunities for outdoor attractions, family excursions and wildlife experiences.

The 119-hectare park in Al Warqa is home to more than 3,000 animals representing about 300 species across six themed zones. Its attractions include safari journeys, animal encounters and live presentations that combine entertainment with education about wildlife and conservation. The Park typically closes during the hotter summer months and resumes operations in October.

The reopening was timed to coincide with the UAE school mid-term break, with a special programme running from 12 to 18 October. Dubbed the “Wildest Opening Week”, the programme included children’s activities, live performances, safari-themed games and interactive experiences designed to draw families during the holiday period.

Beyond the opening-week events, the park offers visitors different ways to experience its animal habitats. The Arabian Desert Safari is included in the standard admission ticket, while the Safari Bundle includes the Explorer Safari Tour. Premium options include private guided tours and behind-the-scenes experiences, giving visitors alternatives at different price points.

The attraction adds to Dubai’s range of outdoor activities during the cooler months, when the emirate’s tourism offering extends beyond shopping malls, indoor entertainment and large-scale events. For visitors travelling with children, attractions that can occupy several hours may also influence how families structure their itineraries and how long they spend in the destination.

For Kenya’s outbound travel market, the reopening provides another activity that can be incorporated into Dubai family holidays during the December school break and the wider winter travel season. Its commercial value will depend on how well it fits with flight schedules, accommodation, transfers and other attractions in a package, as well as the overall cost to families.

The Park is open daily from 9 am to 6 pm during the season, with last entry at 5 pm. The standard Safari Park Pass starts at AED 50, while the Safari Bundle is listed at AED 117. Travellers should confirm ticket inclusions, available experiences and prices before booking.

KLM Schedules Airbus A350 Flights to Nairobi and Tanzania

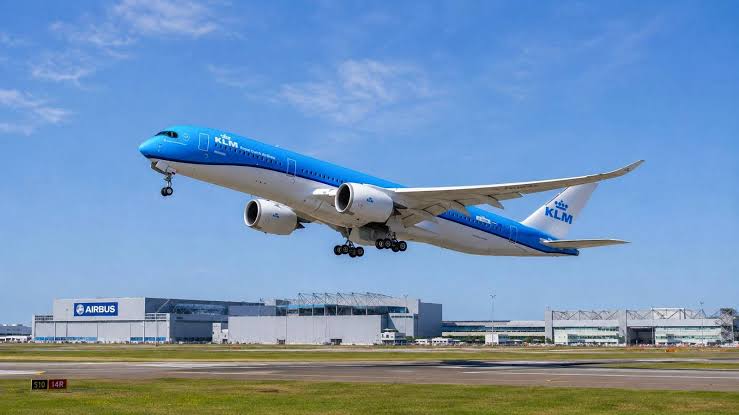
KLM will introduce its Airbus A350-900 on selected Amsterdam–Nairobi flights from January 2027, while also deploying the aircraft on its Amsterdam–Kilimanjaro–Dar es Salaam service, bringing a new aircraft type to key East African routes in its winter schedule.

The Dutch carrier plans to operate the A350-900 to Nairobi three times a week from 5 January 2027, according to schedule filings reported by aviation schedules specialist AeroRoutes on 15 October. The aircraft is expected to replace the Boeing 787-10 on selected rotations rather than cover the entire Nairobi service.

The change will give passengers travelling between Kenya and the Netherlands access to KLM’s newest long-haul aircraft on selected departures. The airline has not announced an increase in the overall frequency of its Amsterdam–Nairobi route alongside the aircraft deployment.

The A350 will also operate on the airline’s Amsterdam–Kilimanjaro–Dar es Salaam routing from December 2026. The schedule calls for two weekly A350 services from 15 December, reducing to one weekly from 6 January 2027 before increasing to two weekly from 26 February and three weekly from 6 March.

The changes are part of KLM’s wider introduction of the A350-900 across its long-haul network as it adjusts aircraft assignments for the northern winter 2026/27 season.

What the aircraft change means for Nairobi

The Airbus A350-900 is a long-haul widebody aircraft designed for fuel efficiency and passenger comfort. Its deployment on selected Nairobi flights gives KLM another aircraft option on a route connecting Kenya with Amsterdam, one of Europe’s major aviation hubs.

For Kenyan travellers, Amsterdam provides onward connections to destinations across Europe and other international markets. The aircraft change may affect the cabin product and the number and type of seats available on individual departures, depending on the final configuration and operating schedule.

KLM’s initial A350-900 configuration is listed as 34 business-class seats, 26 premium-economy seats and 271 economy seats, giving a total of 331 seats. This is the published configuration for the aircraft type in its initial deployment; travellers should check the specific flight before booking because aircraft and cabin assignments can change.

The aircraft’s arrival does not, by itself, mean that KLM is adding capacity to Nairobi. The A350 is scheduled to replace the 787-10 on selected flights, making this primarily an equipment change rather than a confirmed increase in frequencies or total seats offered across the route.

For travel agents and corporate travel managers, the relevant consideration will be which departures receive the A350 and whether the cabin product meets customers’ requirements. Passengers choosing business or premium economy should verify the aircraft assignment and seat availability for their travel dates.

Tanzania deployment follows a phased schedule

KLM’s Tanzania operation will also see a phased A350 introduction on the Amsterdam–Kilimanjaro–Dar es Salaam route. The changing number of weekly A350 rotations means the aircraft will not necessarily operate every flight on the route.

Kilimanjaro serves visitors travelling to northern Tanzania’s safari circuit, while Dar es Salaam is an important gateway for business and onward travel. The combined routing connects both destinations to Amsterdam, allowing KLM to serve different travel markets within one operating pattern.

The planned deployment is relevant to the region’s tourism trade because aircraft type can influence the cabin experience and seat availability on particular dates. However, the impact on total capacity depends on the aircraft being replaced and the number of flights operated, not simply on the introduction of a newer aircraft.

A fleet transition to watch

KLM’s schedule filings show that its A350 rollout is being introduced route by route rather than as a single network-wide change. Nairobi is scheduled to receive the aircraft three times weekly from January, while the Tanzania routing moves through several frequency changes between December and March.

As with all advance airline schedules, the filed aircraft and operating dates remain subject to revision. The development is therefore best understood as a planned change to the aircraft deployed on selected East African flights, rather than a confirmed expansion of KLM’s overall service to the region.

Source: AeroRoutes

TAAG’s Guangzhou Expansion Puts Nairobi’s Luanda Connection in Focus

TAAG Angola Airlines’ weekly service to Guangzhou is opening another potential long-haul connection through Luanda, giving Kenyan travellers an additional routing to southern China while strengthening the commercial relevance of the airline’s three-times-weekly Nairobi link.

The strategic importance of TAAG Angola Airlines’ Guangzhou service for Kenya lies not only in the new China connection, but in how it fits into the carrier’s existing Nairobi operation. With direct flights linking Nairobi and Luanda, the Angolan airline has a potential platform for connecting East African passengers to its growing intercontinental network.

TAAG launched its direct Luanda–Nairobi service on 1 September 2025, initially scheduling three flights a week using the Airbus A220-300. The aircraft has 137 seats: 12 in business class, 35 in premium economy and 90 in economy. The route was introduced to strengthen links between Southern and East Africa, with Nairobi identified by the airline as an important regional hub.

The airline subsequently added Guangzhou to its network in June 2026, connecting Luanda with one of China’s principal manufacturing and trading centres. The service was launched with the Boeing 787-9 Dreamliner before switching to the Boeing 777-300ER from 29 September. The Guangzhou route is currently scheduled once weekly.

For Kenyan passengers, the combination creates a potential itinerary from Nairobi through Luanda to Guangzhou. However, the commercial usefulness of the connection depends on whether the flight schedules align, whether tickets can be issued for the complete journey and how baggage and onward connections are handled. The existence of both routes does not, on its own, establish a guaranteed or seamless connection.

Nairobi’s role in TAAG’s wider network

The Nairobi route gives TAAG a direct presence in East Africa, linking Kenya’s principal international gateway with Angola’s new Dr Antonio Agostinho Neto International Airport in Luanda.

The route was launched with three weekly frequencies and a flight time of about four hours. That frequency gives passengers several weekly options to travel between the two cities, while providing a potential feeder market for TAAG’s services beyond Angola.

Luanda’s value to Kenyan travellers depends on the breadth and scheduling of TAAG’s onward network. The airline serves destinations across Africa and operates long-haul routes beyond the continent, including services to Europe and Brazil. A connection through Angola may therefore be relevant to travellers comparing routing options, although each itinerary must be assessed against available flights, total journey time and fares.

Guangzhou adds a particularly significant destination to this network because of its role in international manufacturing and trade. The city attracts buyers, distributors, wholesalers and business visitors seeking contact with Chinese suppliers. Kenya’s importers and traders are among the groups for whom an additional routing could be worth evaluating.

The opportunity is not limited to business travel. A China connection could also serve other passengers travelling for education, family visits or leisure, provided the schedules and fare conditions are competitive.

A larger aircraft on the China sector

TAAG’s aircraft change on the Guangzhou route is another relevant development. The Boeing 787-9 was replaced by the Boeing 777-300ER from 29 September 2026, while the published frequency remained at one flight per week.

The change means that the aircraft deployed on the China route has changed, but it should not automatically be interpreted as an increase in capacity or evidence of stronger demand. Aircraft seat counts and cabin layouts vary by configuration, and the airline has not publicly explained the reason for the substitution in the cited schedule report.

For Kenyan travel agents, the more immediate consideration is the weekly frequency. Passengers travelling to Guangzhou through Luanda must plan around the operating day and check the connection in both directions. A weekly long-haul service offers less flexibility than a daily operation, particularly for travellers with fixed business appointments or short trips.

The connection also needs to compete with existing Nairobi–China options. China Southern operates nonstop Guangzhou–Nairobi services, with its schedule expanded to daily flights from July 2026. This gives Kenyan travellers a direct alternative and places pressure on connecting itineraries to offer competitive fares, convenient timings or other advantages.

What the route means for Kenya’s travel trade

TAAG’s Guangzhou service gives Kenyan travel businesses another itinerary to examine when planning journeys between Nairobi and China. Its value will depend on the availability of coordinated connections through Luanda, the total journey time, fare competitiveness and the reliability of the operating schedule.

For corporate travel managers and agents serving importers, wholesalers and manufacturers, the route could offer an alternative where dates and connections work. Agents should distinguish between a bookable through-ticket and separate flights requiring passengers to manage their own transfer arrangements.

The wider opportunity is to monitor whether TAAG develops the Nairobi–Luanda connection alongside its long-haul expansion. More frequent Nairobi flights, improved connection times or additional onward destinations could strengthen Luanda’s usefulness to East African travellers. Conversely, limited frequency on the Guangzhou sector may restrict the number of itineraries that can be offered conveniently.

For now, the clearest development is the addition of Guangzhou to TAAG’s network and the potential it creates for passengers travelling from Kenya through Luanda. The extent to which that becomes a commercially significant Nairobi connection will depend on schedules, fares, distribution arrangements and the airline’s future frequency decisions.

West African Visitors Outspend European Markets on Kenya Accommodation

West African visitors spend an average KSh10,410 a day on accommodation in Kenya, exceeding the daily lodging expenditure recorded among visitors from the UK, Switzerland and the US, according to a Kenya National Bureau of Statistics survey.

The findings point to an opportunity for Kenya’s tourism industry to pay closer attention to African source markets as hotels, travel agents and tour operators seek to increase revenue from international visitors.

Data show that visitors from West Africa recorded the highest average daily accommodation expenditure among the regional groupings highlighted in the survey. North African visitors followed at KSh8,627, while visitors grouped under East and Central Africa spent KSh8,492 a day.

The West African average was about 22 per cent higher than the North African figure and 23 per cent above the East and Central African average.

The regional comparison also placed West African visitors ahead of several established Western markets. Visitors from Switzerland spent an average KSh7,779 per day on accommodation, compared with KSh7,511 for the UK and KSh7,177 for the US.

West Africa’s average was therefore approximately 34 per cent higher than the UK figure and 45 per cent above the US figure.

The survey identified visitors from countries including Nigeria and Cameroon among those contributing to the West African spending pattern. However, the regional average should not be interpreted as the spending level of every nationality or individual visitor within the group.

Accommodation demand grows as hotel stays increase

The spending figures come against a backdrop of rising demand for accommodation. Kenya recorded 11.56 million hotel-bed nights in 2025, up from 10.26 million in 2024, an increase of 12.7 per cent.

Hotel-bed nights have more than doubled since 2021, when they stood at 5.52 million. The total rose to 7.01 million in 2022 and 8.63 million in 2023 before reaching 11.56 million in 2025.

The growth suggests that accommodation demand has continued to recover and expand beyond the immediate post-pandemic period. For the sector, the next question is how effectively that demand translates into higher yields for accommodation providers and other tourism businesses.

The accommodation and food service industry contributed 1.7 per cent of Kenya’s gross domestic product in 2025, compared with 1.6 per cent in 2024 and 1.3 per cent in 2023, according to the figures cited by Business Daily.

The rise in hotel-bed nights and the industry’s GDP contribution provide broader context for the accommodation-spending data, although neither measure establishes how much of the growth came from West African visitors.

Travel purpose shapes spending

The KNBS survey also shows that accommodation expenditure varies according to the purpose of travel, creating another distinction for tourism businesses assessing which customers to target.

Visitors in transit recorded average daily accommodation spending of KSh8,233, narrowly ahead of those travelling for meetings, incentives, conferences and exhibitions (MICE), at KSh8,198.

Business and professional visitors spent an average KSh6,565 per day, while holidaymakers recorded KSh5,630.

The figures suggest that demand associated with business travel, conferences and transit can generate accommodation expenditure comparable to, or higher than, that of some leisure segments. They also show why source-market data alone is insufficient: the reason for travelling can materially affect spending.

For Kenyan hotels and travel businesses, combining information about visitors’ country of residence with their travel purpose could help identify opportunities in conference travel, corporate accommodation, stopovers and leisure extensions.

The accommodation figures should not, however, be confused with total visitor expenditure. In a separate report based on KNBS data, Business Daily put average daily expenditure across all categories of inbound tourist spending at KSh19,306. That broader measure includes expenditure beyond accommodation, such as transport, food, shopping, entertainment and tours.

Hotels remain the leading accommodation choice

Hotels accounted for 52.1 per cent of visitors in the survey’s accommodation-facility breakdown, making them the dominant category.

Staying with friends or relatives accounted for 25.6 per cent, while vacation rentals, including Airbnb properties, represented 9.6 per cent. Lodges accounted for 9.4 per cent, apartments 5.4 per cent and campsites 2.9 per cent.

The distribution shows that Kenya’s accommodation market extends beyond conventional hotels, although hotels remain the largest single category.

For travel agents and tour operators, this creates scope to match accommodation options to trip purpose, length of stay and customer preferences. Business travellers and conference delegates may require centrally located hotels, while leisure visitors may favour resorts, lodges or combinations of properties across several destinations.

The figures do not establish which accommodation types West African visitors prefer. That would require a more detailed breakdown by nationality, travel purpose and facility type.

African markets warrant closer attention

The West African spending figures challenge the assumption that higher-value accommodation demand necessarily comes from Europe or North America. They indicate that African visitors can represent a commercially important market, even where their home countries have lower average incomes than some traditional Western source markets.

Business Daily noted that Nigeria and Cameroon have substantially lower GDP per capita than the US and Switzerland, yet the West African regional group recorded higher average daily accommodation expenditure than visitors from those two countries. National income levels alone, therefore, do not determine what visitors spend while travelling abroad.

For Kenyan travel businesses, the implication is to assess African markets using actual visitor expenditure, arrival volumes, travel patterns and length of stay rather than relying on assumptions about purchasing power.

Nigeria, Ghana and neighbouring countries may offer opportunities across Nairobi accommodation, corporate travel, MICE, shopping, coastal holidays and safari packages. But the spending data alone does not prove that each market is growing or that every visitor is seeking a premium product. Commercial decisions would need to be supported by country-level arrival statistics, air connectivity, booking data and customer research.

The distinction between high daily expenditure and total market value is also important. A market with high spending per visitor may still generate less aggregate revenue if visitor numbers are relatively small or stays are short. Conversely, a larger market with lower daily expenditure may contribute more in total.

For Kenya’s tourism industry, the figures provide a useful starting point for examining where accommodation revenue is being generated. The opportunity is to connect that spending intelligence with reliable source-market data and develop products that respond to identifiable demand.

Source: Business Daily

From Classroom to Career: Travelport’s Long Investment in Kenya’s Travel Talent

From early efforts to introduce tourism students to reservation technology to university partnerships, instructor training and aviation workforce development, Travelport’s education initiatives reflect a long-standing challenge for Kenya’s travel industry: preparing graduates for the realities of the workplace.

When Travelport began exploring the introduction of its Galileo Graduate programme to Kenyan colleges in 2010, the objective was to give tourism students practical skills in airline reservations and ticketing before they entered the job market.

The five-day programme, developed for incorporation into existing tourism courses, combined classroom instruction with hands-on system training. Students who passed an examination received a Travelport certificate demonstrating working knowledge of Galileo, the global distribution system used to book and manage travel.

Contemporary industry reporting identified Kenya as one of the markets Travelport was considering after introducing the programme in Mauritius. The available record confirms discussions with Kenyan colleges, rather than a completed rollout at that time.

More than a decade later, the same question remains central to tourism education: how can institutions ensure that students graduate with the practical knowledge, technology skills and commercial understanding required by travel businesses?

Travelport’s subsequent initiatives in Kenya offer a way to examine how that challenge has been addressed, from introducing young people to travel technology to supporting training institutions and creating opportunities for industry exposure.

From career awareness to classroom technology

A significant development came in 2012, when Travelport joined the Global Travel & Tourism Partnership (GTTP), an international education initiative designed to introduce young people to careers in the travel and tourism industry.

The partnership extended Travelport’s involvement beyond reservation systems to career awareness and educational content. At the time, GTTP reported that its programmes had reached more than 1.5 million students across 12 countries.

Kenya was among the countries participating in the GTTP network, providing a platform through which global industry expertise could be connected to local schools.

In April 2013, Travelport established a direct operation in Kenya. The company said Galileo had been present in East Africa since 1997, previously distributed through Kenya Airways. A direct presence strengthened its local commercial and support operations.

That year, Travelport worked with GTTP Kenya on an initiative to expose teachers to technology used across the global travel industry.

A two-day workshop in Nairobi brought together teachers from four counties for practical engagement with travel technology. The intention was for educators to take that knowledge into their classrooms and help students understand how technology supports the traveller journey and creates career opportunities beyond traditional travel agency roles.

The initiative also contributed to GTTP’s Passport to the World curriculum, which included a unit on technology used by travel professionals.

This approach was significant because it addressed more than students’ immediate technical skills. By supporting teachers and educational content, Travelport was helping build the capacity to introduce travel technology to successive groups of learners.

The African Development Bank’s 2013 Africa Tourism Monitor also documented GTTP Kenya’s presence in schools across the country, identifying Travelport among the international companies supporting the wider programme.

By 2016, GTTP reported that more than two million students globally had participated in its programmes. Travelport’s involvement included curriculum development and training related to the digital economy, according to the partnership’s anniversary account.

The Kenyan experience formed part of a broader model linking industry knowledge with education, although the publicly available record does not establish the scale of Travelport’s individual contribution to Kenyan schools over every subsequent year.

The case for practical distribution skills

For travel agencies and other tourism businesses, technology training has a direct commercial dimension.

Reservations, fares, ticketing and the management of travel content require familiarity with systems used by professionals. A graduate may understand tourism theory but still need practical training to perform these tasks in a working environment.

Travelport’s historical college training materials reflect this distinction, combining fares-and-ticketing instruction with e-learning and access to Galileo systems.

The approach also included training for educators, allowing instructors to become more familiar with the technology they were expected to teach.

That model remains relevant as distribution technology evolves. Travel professionals increasingly need to understand not only how to make bookings but also how to work with changing airline content, digital tools and customer expectations.

In Kenya, Travelport technology is now incorporated into formal training pathways offered through several institutions associated with IATA qualifications. These include Kenya Utalii College, the East African School of Aviation and Nairobi Aviation College, which list Travelport-related travel and tourism training.

Universities gain access to industry systems

In July 2025, Mount Kenya University recorded a partnership with Travelport Services Kenya through its School of Hospitality, Travel and Tourism Management.

The publicly stated elements included access to the Travelport system, software and associated documentation.

The arrangement reflects a shift towards giving educational institutions access to tools used in the industry, rather than relying exclusively on theoretical instruction or demonstrations.

For universities, access to industry systems can provide students with opportunities to develop familiarity with travel distribution before entering employment. For travel technology providers, institutional partnerships create a channel through which future professionals can encounter their products while training.

The practical value of such arrangements ultimately depends on how the technology is integrated into coursework, how frequently students use it and whether their proficiency is assessed against workplace requirements.

Extending training into the aviation workforce

The education-to-employment question also features in the partnership between Kenya Airways and Travelport at the Kenya Airways Pride Centre.

In November 2025, more than 40 trainees graduated from IATA-aligned programmes, with Travelport providing access to distribution and retailing technology.

The training covered areas including digital ticketing, customer service, ground operations, sustainability, cargo and logistics management, alongside modern airline distribution platforms.

The arrangement brought together different areas of expertise: Kenya Airways’ aviation experience and training environment, IATA-aligned instruction, and Travelport’s distribution technology.

The significance is that learners were exposed to systems and processes relevant to professional aviation and travel operations, extending the education discussion beyond schools and universities.

The programme represents a more specialised stage of workforce preparation, although the number of graduates alone does not establish subsequent employment or long-term career outcomes.

Training the trainers and equipping institutions

At the second Kenya Travel and Tourism Students Symposium in 2026, Travelport highlighted ongoing Training of Trainers programmes with Kenya Utalii College, computer donations to learning institutions and access to self-training courses.

The symposium, organised by the Kenya Association of Travel Agents (KATA) at Strathmore University, brought together more than 170 students from 20 learning institutions.

Travelport’s contribution focused on connecting students with the technology and professional practices they will encounter in the travel industry.

Training instructors can extend the reach of that work. Rather than limiting technical instruction to individual workshops, developing lecturers’ familiarity with industry systems can help institutions deliver relevant training to successive cohorts.

Computer donations address another practical requirement: students need access to suitable equipment to practise using digital reservation and distribution systems.

Self-training courses provide an additional route for learners to develop their knowledge outside scheduled classroom sessions.

Connecting students with employers

The KATA symposium also illustrated how technology providers and airlines can contribute to career exposure beyond formal training.

Travelport representative Isaac Mukuru outlined the company’s education initiatives, while Safarilink Aviation used the event to introduce students to the range of careers available within an airline.

Capt. Ryan Gitonga Kithinji, Safarilink’s Training Captain and Designated Check Pilot, encouraged students to build their skills and demonstrate the value they could bring to an organisation. The airline also highlighted internship and industrial attachment opportunities.

The distinction is important in an industry that encompasses far more than travel sales or flight operations. Careers span customer service, marketing, commercial management, logistics, technology and other functions that support the movement of travellers.

For KATA, bringing employers and industry partners into the learning environment creates an opportunity for students to understand these roles before making career decisions.

The symposium also placed technology within a wider discussion about employability. Speakers stressed that familiarity with digital tools must be accompanied by communication, judgement, adaptability and the ability to solve problems.

These capabilities become particularly relevant as artificial intelligence changes how travel products are searched, compared and sold.

Measuring the value of the education pipeline

The available record shows several distinct strands of Travelport’s engagement with education and talent development: early discussions about college-level Galileo training, support for tourism education through GTTP, curriculum and teacher development, access to systems through institutional partnerships, specialised aviation training and more recent engagement with students and instructors.

Together, these initiatives point towards an education-to-employment model that connects career awareness with practical skills and industry exposure.

But demonstrating its full economic value requires more than a list of programmes. Data on the number of learners trained, qualifications earned, institutions supported, graduate placements and employer feedback would help establish whether the initiatives are improving workforce readiness and employment outcomes.

It would also clarify how much of the work has been sustained over time, particularly during periods for which publicly accessible records of specific Kenyan initiatives are limited.

For the travel industry, the underlying challenge remains clear. Tourism qualifications provide a foundation, but employers also need graduates who can use relevant systems, understand commercial operations and respond to the needs of travellers.

Travelport’s experience in Kenya offers a case study in how a technology provider can contribute to that process by working with schools, colleges, universities, instructors, airlines and industry associations.

The next measure of progress will be how effectively these connections translate into practical competence, stronger recruitment pathways and professionals equipped to help Kenya’s travel industry compete in an increasingly digital market.