Saudi Arabia has suspended the issuance of all visa categories to travellers from Kenya and barred entry to passengers arriving from the country, disrupting travel between the two markets following concerns over the Ebola outbreak.
The restrictions, announced on October 30 following an assessment by Saudi health authorities, also suspend travel by Saudi citizens to Kenya, introducing new uncertainty for passengers travelling between the two countries for business, religious purposes, employment and family visits.
Under the measures, travellers arriving in Saudi Arabia through third countries are also barred from entry if they have stayed in Kenya or another country experiencing an Ebola outbreak within the 21 days preceding their arrival.
The provision means that routing through another destination does not automatically exempt passengers from the restrictions. It also places additional responsibility on airlines and travel agents to establish passengers’ recent travel histories before confirming their journeys.
The decision was reported by Saudi Gazette following an announcement by the Saudi authorities. The Saudi Public Health Authority, known as Weqaya, said the measures were part of continued monitoring of regional and international health developments and that the health situation within the Kingdom remained stable.
The restrictions come as Kenya manages an outbreak of Bundibugyo virus disease, a strain of Ebola.
The World Health Organisation (WHO), in its October 23 situation update, reported nine confirmed cases in Kenya, including one death, as of October 20. The eight additional cases were linked to the initial imported case, with no evidence of transmission outside the identified cluster at the time.
Kenya’s Ministry of Health subsequently reported on October 30 that the country had gone 10 days without recording a new infection. All nine confirmed cases were linked to the same cluster, while authorities continued monitoring contacts and implementing containment measures.
The development presents a challenge for Kenya’s aviation and travel industry, particularly agencies handling Saudi-bound passengers. The market serves several travel segments, including business, employment, religious travel and visits to family members.
For travel agents, the immediate concern is the treatment of existing bookings, newly issued tickets and passengers whose travel dates fall within the restriction period. Agencies will need to establish the applicable arrangements with airlines and verify entry eligibility before issuing or changing tickets.
The 21-day provision also complicates itinerary planning for passengers connecting through other international hubs. A change of departure point will not overcome the restriction where the passenger’s recent presence in Kenya or another affected country remains within the specified period.
Saudi Arabia has previously introduced similar measures involving the Democratic Republic of Congo, Uganda and South Sudan in June 2026, extending its precautionary approach to countries considered to face Ebola-related risks.
The WHO, however, has advised against restrictions on travel and trade with affected countries, favouring coordinated surveillance, early detection and public health preparedness.
For Kenya, the Saudi decision underscores how a public-health event can quickly extend beyond the health sector, affecting international connectivity, tourism and commercial relationships.
The duration of the restrictions and the conditions for their removal had not been specified in the announcement, leaving airlines, travel agencies and affected passengers awaiting further guidance from Saudi authorities.
More than half of African travellers have been discouraged from visiting a destination because of immigration requirements, exposing a growing barrier to tourism growth as countries compete for international visitors.
The International Air Transport Association’s (IATA) 2026 Global Passenger Survey found that 52 per cent of African respondents had been deterred from visiting a destination because of entry requirements, the highest proportion of any region surveyed. Globally, the figure stood at 43 per cent, up from 33 per cent in 2025.
The findings, released on October 28, highlight how visa procedures, documentation requirements and processing costs are increasingly influencing destination choices, sometimes before travellers even make a booking.
Complexity was the biggest concern among affected passengers, followed by cost. Globally, 53 per cent of respondents who had been discouraged by immigration requirements cited complexity, while 17 per cent identified cost and another 17 per cent cited privacy concerns.
For African tourism markets, the implications extend beyond immigration administration. A traveller comparing destinations may ultimately choose a country with simpler entry procedures over one requiring lengthy applications, extensive documentation or uncertain processing timelines.
This places immigration accessibility alongside air connectivity, accommodation costs and destination experiences as a factor influencing tourism competitiveness.
The survey also revealed strong African passenger interest in digital travel solutions that could simplify international journeys.
Some 87 per cent of African respondents expressed interest in using digital passports for online check-in, compared with the global average of 84 per cent. Additionally, 82 per cent were willing to share biometric information if it meant avoiding repeated presentation of passports and boarding passes at airport checkpoints.
Globally, 86 per cent of passengers said they would be likely to share immigration information digitally before departure to accelerate processing. Meanwhile, 60 per cent preferred applying for visas online rather than visiting embassies or consulates.
The findings suggest that passengers are increasingly willing to embrace technology, but immigration systems have yet to deliver the seamless experience they expect.
For African countries seeking to expand international arrivals and intra-African tourism, simplifying entry procedures could become an important competitive advantage. Electronic visa systems, predictable processing times and interoperable digital travel credentials could reduce friction for visitors while improving the efficiency of border operations.
Kenya has already moved towards digital entry processing through its Electronic Travel Authorisation system, introduced in January 2024 to replace the previous visa application process for most foreign visitors. However, the wider challenge remains ensuring that digital procedures are straightforward, accessible and predictable.
The findings also create an opportunity for travel agencies to strengthen their documentation advisory services. Visa requirements increasingly influence destination selection, making accurate entry information and assistance with applications valuable additions to travel planning. However, governments remain responsible for simplifying immigration procedures.
IATA’s survey, based on more than 10,000 responses from over 200 countries, points to a fundamental issue for the continent’s tourism industry: improving connectivity alone will not be enough if travellers find destinations difficult to enter.
With 52 per cent of African respondents reporting that immigration requirements had discouraged them from visiting a destination, easing border formalities could be as important to attracting visitors as expanding flights and promoting tourism products.
Source: International Air Transport Association (IATA)
Skyward Airlines has reinstated a 3 per cent commission on eligible ticket sales through its Travel Agent Booking Portal, reopening a long-running debate over how airlines compensate travel agents for distributing their products as the industry moves towards direct bookings and technology-driven sales.
The commission applies to the base fare of tickets issued by registered and authorised travel agents through the airline’s designated portal. Taxes, airport charges, levies and ancillary fees are excluded.
The decision offers travel agencies a new revenue opportunity, but its significance extends beyond the additional earnings. It comes against a history of declining airline commissions, the introduction of service fees and performance-based incentives, and growing differences in how carriers reward agencies across international markets.
From standard commissions to zero commission
Airline commissions were once a central component of the travel agency business model. Agents sold tickets on behalf of carriers and received a percentage of the fare as remuneration for marketing, distribution, booking and ticketing services.
In international markets, commission rates historically averaged between 6 and 7 per cent before the mid-1980s. In the United States, rates subsequently rose to 10 per cent during a period of intense competition for agency business.
That model began to change in 1995 when Delta Air Lines introduced commission caps, triggering a series of reductions across the industry. By 2005, most major US and many international airlines had adopted zero-base-commission policies, according to the publication.
The change shifted much of the responsibility for agency remuneration towards customer service fees and privately negotiated commercial agreements between airlines and larger travel agencies.
Instead of receiving a standard percentage on every ticket, some agencies began earning performance-based overrides tied to sales volumes, market share, particular fare categories and revenue targets.
The system remains in place in different forms across global markets. Large agencies can negotiate commissions and additional incentives with individual airlines, while smaller agencies may receive no standard commission from some carriers.
The result is that airline commission is no longer a uniform industry-wide entitlement but a commercial arrangement shaped by individual airline strategies and agency performance.
Kenya’s experience with commission cuts
Kenya’s travel trade has experienced the same transition.
In 2007, British Airways reduced its agency commission in Kenya from 7 per cent to 1 per cent, before announcing its intention to eliminate the remaining commission from February 2009.
The decision prompted protests from the Kenya Association of Travel Agents (KATA), with the association arguing that agents were providing distribution and sales services on behalf of airlines and should be compensated for that work.
British Airways maintained that the changing industry environment required travel agents to determine their own service charges and obtain compensation directly from customers.
The dispute reflected a wider change in the airline-agency relationship: airlines increasingly viewed agents as independent service providers whose income could come from passengers rather than from the carrier.
Research published in 2021 by scholars from Moi University examining Kenya Airways’ strategies following its zero-commission policy also documented the industry’s adjustment. It identified internet distribution, corporate travel, branding and yield management among the approaches used to sustain ticket sales in the changed environment.
The development of online booking platforms gave airlines another route to reach passengers directly, although it did not eliminate the role of travel agencies in corporate travel, complex itineraries and other specialised bookings.
The commercial value of the agency channel
Despite the growth of direct airline sales, travel agencies remain an important distribution channel in Kenya.
IATA’s Billing and Settlement Plan (BSP) data, as reported by KATA, shows that accredited travel agencies processed more than Sh74 billion in airline ticket sales in Kenya in 2025.
Globally, the BSP handles more than US$240 billion in annual settlements, connecting hundreds of airlines with tens of thousands of accredited travel agencies.
These figures represent the scale of transactions passing through the agency settlement system, not the revenue earned by travel agents. However, they illustrate the commercial reach of the distribution network available to airlines through accredited agencies.
For carriers, the agency channel provides access to corporate accounts, government travel, tour operators, group bookings and customers who require assistance navigating multiple airlines and complex itineraries.
For travel agents, airline commissions and incentives can help offset the cost of maintaining booking systems, trained personnel, customer support and after-sales services, including ticket changes and refunds.
The economics are relevant in Kenya, where corporate and government travel often involves credit arrangements and delayed customer payments. Agencies may have to issue tickets and meet airline settlement obligations before receiving payment from their clients.
This means the commercial value of an airline relationship extends beyond the commission percentage. Payment terms, access to inventory, booking technology, ticketing support and incentives can all influence the cost and profitability of distributing a carrier’s products.
A global market with different remuneration models
The international market illustrates how airline remuneration has evolved beyond a single commission structure.
In the United States, major carriers increasingly rely on confidential agreements with larger agencies, combining commissions on selected fare categories with overrides linked to market share and sales performance.
Commissions and overrides at some large agencies can approach 10 per cent of airfares, although such arrangements are negotiated and are not generally available to every agency.
Other carriers have introduced structured remuneration programmes tied to specific booking channels. Australia’s Jetstar, for example, operates a voluntary programme under which approved agents can receive remuneration on eligible bookings made through its Agent Hub and API. Its published conditions exclude bookings made through global distribution systems and call centres.
The examples illustrate that zero base commission does not necessarily mean airlines have stopped paying travel agencies. Rather, remuneration has become more selective, differentiated by distribution channel, agency size, commercial agreements and sales performance.
IATA’s 2026 Passenger Agency Conference Resolutions Manual also makes clear that commission and remuneration levels are determined by individual airlines, reinforcing the importance of commercial agreements between carriers and their distribution partners.
Technology is changing the relationship
The debate is also taking place as airlines invest in New Distribution Capability (NDC) and other digital retailing systems that give them greater control over how their products are displayed, priced and sold.
NDC allows airlines to distribute richer content, including branded fares, baggage options, seat selection and other ancillary services through technology platforms used by travel agencies.
For airlines, this offers greater control over product presentation and distribution costs. For agencies, it creates opportunities to access a wider range of products while maintaining their role in advising customers and managing bookings.
However, access to airline content and the commercial terms attached to selling it remain important considerations for agencies.
Kenya Airways has been expanding access to its NDC content through its trade platform, while Ethiopian Airlines has developed an agency programme covering more than 700 IATA, non-IATA and NDC agencies across more than 60 countries.
The developments point towards a distribution model in which airlines and travel agencies increasingly rely on shared technology infrastructure, even as they negotiate how the resulting sales revenue is divided.
What Skyward’s return means
Skyward’s decision to restore a 3 per cent commission is therefore significant as an example of an airline choosing to remunerate its agency distribution network directly.
The arrangement also gives the carrier an incentive to encourage authorised agents to transact through its booking portal, potentially strengthening direct commercial engagement between the airline and its sales partners.
However, the commission is restricted to eligible tickets issued through the platform. Agents must also comply with the airline’s ticketing and payment policies, while those without active accounts are required to contact the sales team for registration or reactivation.
For Kenya’s travel trade, the development raises a broader question about the sustainability of airline distribution: as airlines continue to expand direct sales and digital platforms, how should the agencies that bring them customers, manage bookings and provide ongoing service be compensated?
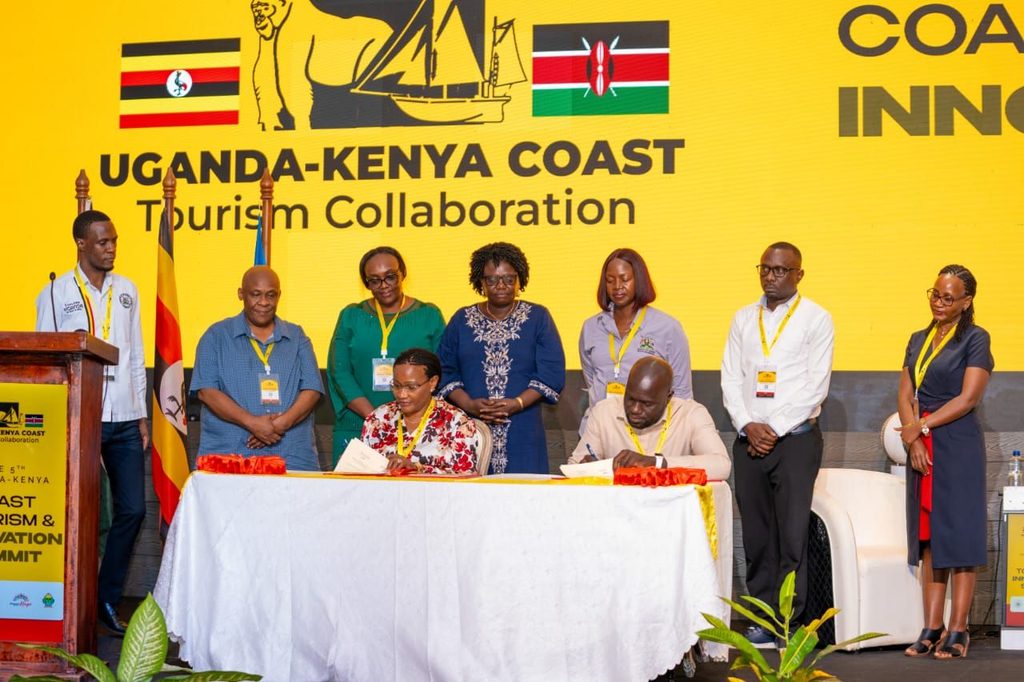
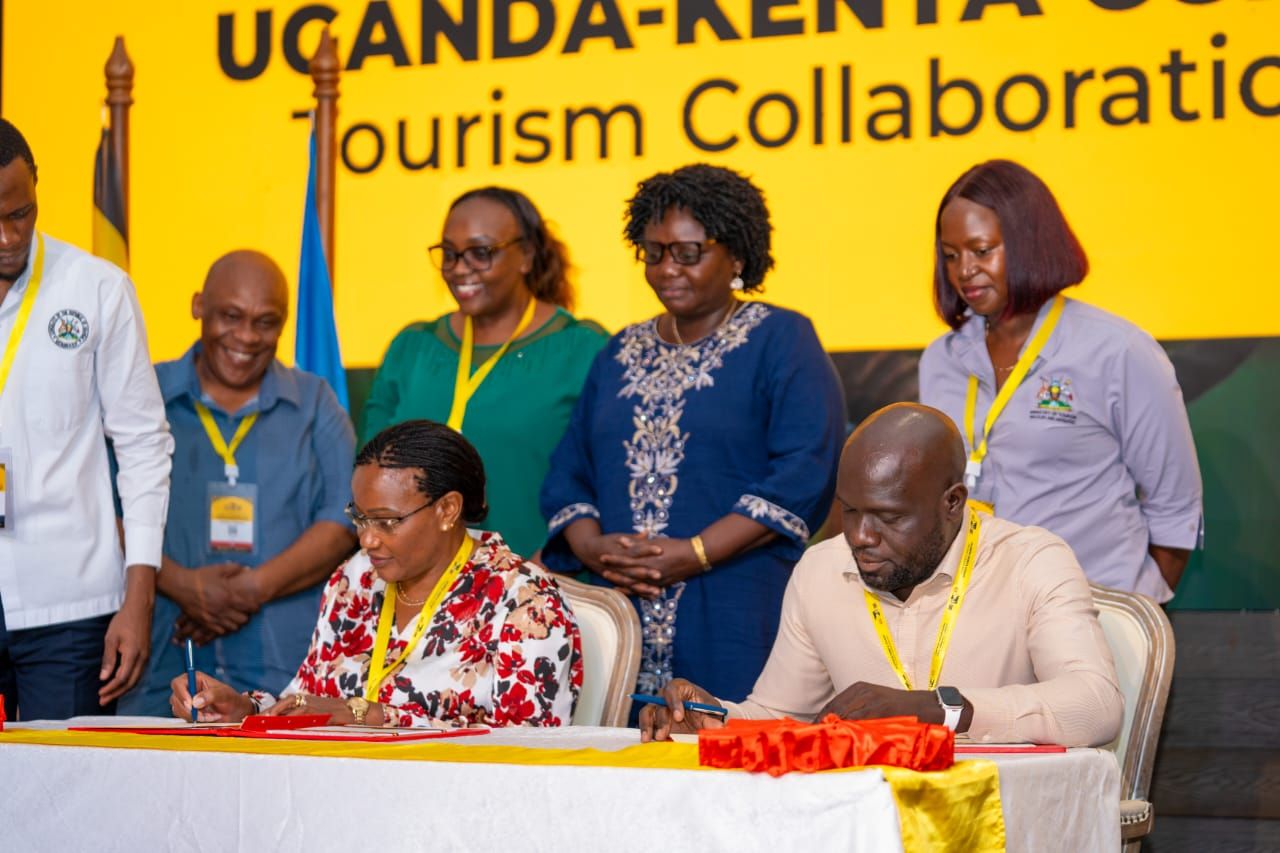
The Kenya Association of Travel Agents (KATA) and the Uganda Association of Travel Agents (TUGATA) have signed a memorandum of understanding to strengthen cross-border tourism business, as visitor movements between the two countries surpassed 750,000 in 2025.
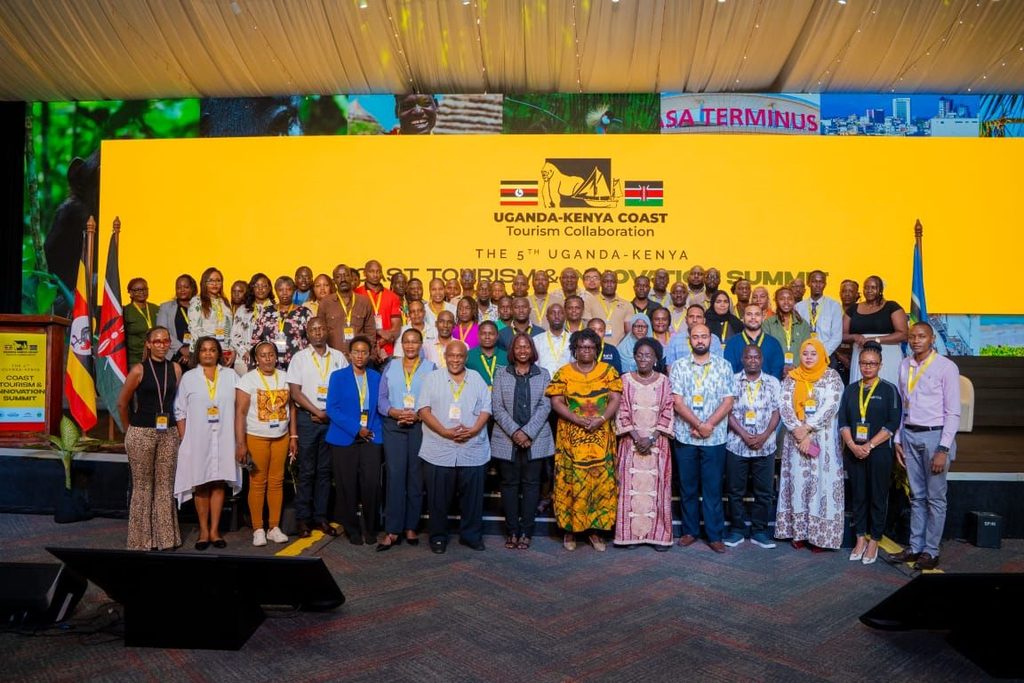
The agreement, signed during the fifth Uganda–Kenya Coast Tourism and Innovation Summit in Mombasa, establishes a framework for cooperation between travel agents in the two markets, with a focus on business partnerships, market access, innovation and the development of regional travel products.
The partnership comes as Kenya and Uganda record growing visitor flows in both directions, creating opportunities for travel agencies and tourism businesses to capture a larger share of regional travel expenditure.
Ugandan arrivals to Kenya increased by 16.3 per cent, from 201,623 in 2024 to 234,556 in 2025, according to Kenya Tourism Board figures. In the opposite direction, Kenyan visitors to Uganda rose by 11.2 per cent, from 466,902 to 519,041, according to Uganda Tourism Board data.
Combined, the two markets recorded 753,597 cross-border visitor arrivals in 2025. The figures point to an established regional travel market, although they represent movements in both directions rather than unique individuals.
Uganda is particularly important to Kenya’s tourism industry, accounting for approximately 31 per cent of arrivals from African markets and ranking among the country’s leading regional source markets.
For Kenya’s travel trade, the growth presents an opportunity to develop packages that extend beyond traditional destination boundaries. Uganda’s mountain gorillas, wildlife reserves, adventure tourism and cultural attractions offer a natural complement to Kenya’s coastal resorts, marine parks and safari circuit.
A traveller could combine a wildlife experience in Uganda with a coastal holiday in Mombasa, while Kenyan visitors to Uganda offer opportunities for agencies to sell gorilla trekking, nature-based tourism and other experiences.
The commercial opportunity, however, extends beyond packaging destinations together. Travel agents on both sides can establish direct supplier relationships, widen their distribution networks and reduce reliance on intermediaries when sourcing accommodation, transport and destination experiences.
KATA Honorary Secretary Margaret Gitonga signed the agreement on behalf of the Kenyan association. The signing took place in the presence of Uganda’s First Deputy Prime Minister and Minister for East African Community Affairs Rebecca Alitwala Kadaga, State Minister for Tourism, Wildlife and Antiquities Susan Nakawuki, and Uganda’s Consul General in Mombasa, Ambassador Herbert Kiguli.
KATA board members Grace Wairimu and Patrick Maina Kamanga also attended the engagement, with Kamanga representing the association’s Coast region.
The agreement builds on efforts by the two associations to strengthen business-to-business relationships between their members and create opportunities for Kenyan travel sellers to connect with Ugandan tourism suppliers.
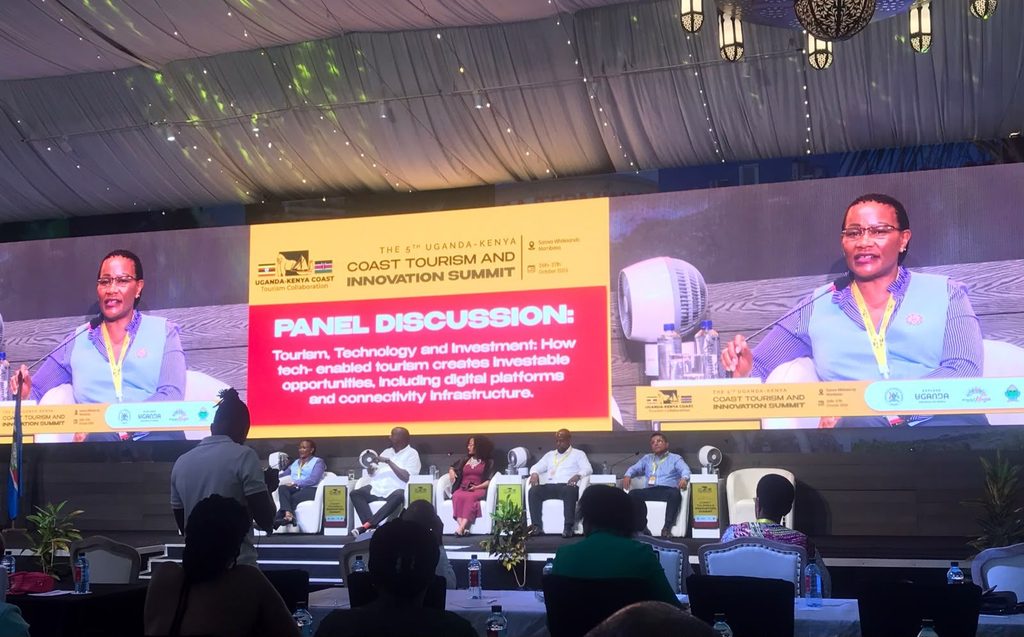
Technology investment also emerged as a central issue during the summit, particularly as travel businesses face changing customer expectations and increasing competition in the distribution of tourism products.
Gitonga, speaking during a panel discussion on tourism, technology and investment, urged travel agencies to invest more substantially in technology, including systems that improve the ability of employees to serve clients.
“We must invest in technology. I encourage my peers (Travel Agents) to substantively invest in technology to enable even our employees to better serve clients,” she said.
For travel agencies, technology investment has implications for how quickly they respond to enquiries, compare travel options, manage bookings and distribute products across different markets. Stronger digital capabilities could also make it easier for Kenyan and Ugandan businesses to collaborate on itineraries and manage bookings involving multiple destinations.
The economic significance of the partnership is reinforced by the wider performance of the two tourism sectors. Kenya generated approximately Sh501.3 billion in tourism earnings in 2025, while Uganda recorded tourism receipts of about Sh5.83 trillion Ugandan shillings, equivalent to US$1.62 billion.
Uganda received 1.64 million international visitors during the year, representing growth of 19.7 per cent, according to its Ministry of Tourism, Wildlife and Antiquities. Kenya, meanwhile, received 2.7 million international visitors, alongside 5.2 million domestic travellers.
These figures illustrate the scale of the tourism economies the two countries can connect through stronger regional trade.
However, increased visitor numbers do not automatically translate into higher earnings for individual businesses. The ability to convert demand into bookings will depend on the availability of competitive packages, reliable transport connections, affordable travel and effective cooperation among tourism suppliers.
The Mombasa summit brought together policymakers, tourism associations, travel agents, tour operators, hoteliers and other private sector players to discuss regional tourism development, innovation, investment and mobility.
For the Kenya Coast, stronger engagement with Uganda offers an opportunity to deepen its regional visitor base beyond traditional international source markets. Direct relationships with Ugandan travel agents could help coastal hotels, resorts, tour operators and transport providers access customers through established distribution channels.
The partnership also creates room for reciprocal promotion of destinations, allowing Kenyan travel businesses to market Uganda while their Ugandan counterparts expand the reach of Kenya’s coastal and safari products.
The challenge now is to translate the memorandum into measurable commercial outcomes, including new supplier agreements, jointly developed itineraries, increased bookings and stronger business relationships between members.
With more than 750,000 recorded visitor movements between the two countries in a single year, the Kenya–Uganda tourism relationship already has a substantial market foundation. The success of the agreement will depend on how effectively the two travel trade associations turn those flows into sustained business for their members.
Kenya Airways has doubled its scheduled daily flights between Nairobi and Dubai for the 2026/27 Northern Winter season, increasing capacity on a route that connects Kenya to one of the Middle East’s major commercial and international travel hubs.
The revised schedule, effective October 25, introduces a second daily service, taking Kenya Airways’ operations to 14 weekly flights in each direction. The flights, KQ304/KQ305 and KQ310/KQ311, are scheduled to operate through late March 2027.
The additional frequency gives passengers more departure options between Nairobi and Dubai, while providing travel agents with greater flexibility when arranging business trips, leisure holidays and onward connections.
Emirates also operates three daily flights between Nairobi and Dubai, equivalent to 21 weekly services in each direction. Together, the two airlines offer a substantial schedule on the route, reflecting its importance for passenger movements between Kenya and the United Arab Emirates.
Dubai serves as a gateway for travellers connecting to destinations across Asia, Europe and the Middle East. The route also supports direct travel for business, trade, shopping and leisure, making it relevant to a broad range of passenger segments.
For Kenya Airways, the additional service increases the number of opportunities to carry passengers on the route and accommodate different departure preferences. For travel agents, the expanded schedule provides more options when matching clients with suitable flight times and onward connections.
The schedule change is a sign of increased planned capacity, although it does not, on its own, quantify passenger demand or establish how full the additional flights are. Actual demand will be reflected in passenger numbers and load factors as the winter schedule progresses.
As airlines expand New Distribution Capability (NDC), the technology standard that is changing how airfares and ancillary services are sold, IATA accreditation remains commercially relevant for travel agencies seeking to manage ticket sales and payments through a common settlement system.
The International Air Transport Association (IATA) confirms that its Billing and Settlement Plan (BSP) services for NDC are available to IATA-accredited travel agents, allowing qualifying transactions to be settled through the same framework used for traditional distribution sales when participating airlines report their NDC transactions through BSP.
The arrangement can consolidate sales reporting, remittance procedures and financial adjustments through BSPLink, reducing the administrative burden of reconciling transactions across different distribution channels. Eligible agents may also access IATA EasyPay and, where applicable, a common financial-security framework covering both traditional and NDC sales.
However, access is not automatic for every NDC booking. Participation depends on the airline’s settlement arrangements, the agency’s eligibility and the applicable commercial and ticketing requirements.
For travel agencies, the distinction matters as airlines expand NDC distribution and businesses assess the cost of maintaining accreditation against the operational benefits it provides. Access to NDC content alone does not guarantee access to BSP settlement, nor does accreditation automatically provide access to every airline’s fares or ticketing facilities.
The commercial decision for agencies is whether accreditation and the services attached to it justify the costs within their particular business model. Factors include ticket volumes, airline relationships, financial-security requirements and the efficiency gained from consolidated reporting and settlement.
As airline distribution evolves, travel agents must assess not only which fares and products they can access, but also how efficiently they can book, pay for, reconcile and service those transactions.
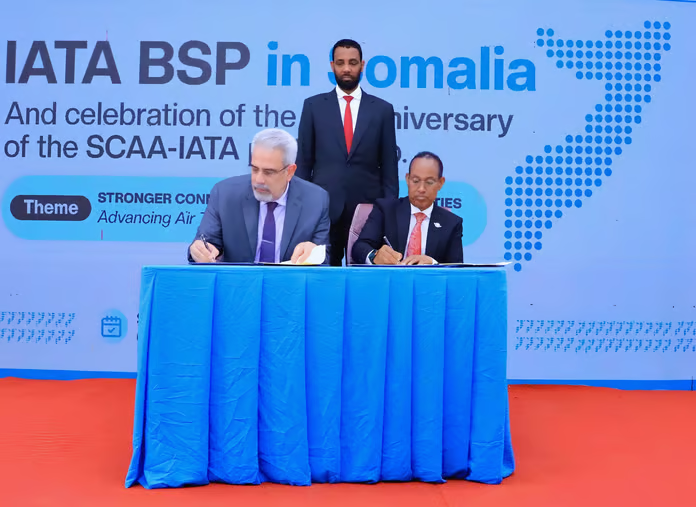
Somalia has formally relaunched the International Air Transport Association’s Billing and Settlement Plan (BSP) after a 35-year absence, restoring a central system for processing airline ticket sales and payments as the country works to rebuild its aviation industry.
The relaunch, held in Mogadishu on October 18, 2026, was attended by Prime Minister Hamza Abdi Barre and senior aviation officials. It coincided with an agreement recognising IATA’s international safety audit programmes for airlines and ground-handling companies, marking two developments in the country’s efforts to strengthen its aviation infrastructure and regulatory framework.
For Somalia’s travel trade, the return of BSP provides a mechanism through which IATA-accredited travel agents can report ticket sales and settle payments with participating airlines through a centralised system rather than managing separate settlement arrangements with individual carriers.
The system could reduce administrative work, improve reconciliation of ticket revenues and give airlines greater visibility over sales and payments in the Somali market. Its commercial value will depend on participation by airlines and accredited agencies, as well as the financial and operational arrangements supporting its implementation.
IATA announced a pilot programme on April 30, 2026, involving four travel agencies and several airlines serving Somalia, including Ethiopian Airlines. At the time, the association said it intended to open the system more widely, targeting more than 300 travel agents operating in the country.
The October relaunch marks the formal return of the settlement system after decades without a domestic BSP arrangement. However, the number of agencies and airlines actively participating following the relaunch has not been publicly confirmed.
A US$242 billion global settlement system
The scale of IATA’s global settlement operations illustrates the importance of the infrastructure being restored in Somalia.
In 2025, BSP processed more than 700 million transactions across over 180 countries, with a total value of US$242 billion, according to IATA. The system serves hundreds of airlines and tens of thousands of travel agents worldwide.
BSP consolidates ticket sales reporting and payments, allowing agents to submit sales information through a central mechanism from which payments are distributed to participating airlines. It also supports the administration of refunds, billing adjustments and other ticketing-related transactions.
For travel agencies, the arrangement can simplify financial reconciliation and reduce the administrative burden of dealing separately with multiple carriers. For airlines, it provides a standardised framework for collecting ticket revenue and monitoring sales through accredited distribution partners.
The system does not eliminate the need for financial controls or guarantee access to every airline. Participation, accreditation requirements and applicable settlement rules remain important conditions for agencies seeking to use it.
Somalia’s reinstatement also has implications for the relationship between local travel businesses and international carriers. IATA has identified the country’s diaspora and expanding trade links across Africa and the Middle East as factors supporting demand for air travel.
A more structured settlement framework could make it easier for participating airlines to work with accredited Somali agencies, although the extent of any resulting increase in bookings or airline capacity remains uncertain.
Safety audits recognised under national regulations
The BSP relaunch coincided with a memorandum of understanding signed on October 18 between IATA, Somalia’s Ministry of Transport and Civil Aviation, and the Somali Civil Aviation Authority.
Under the agreement, the regulator will recognise two IATA audit programmes as acceptable means of demonstrating compliance with national regulations: the IATA Operational Safety Audit (IOSA) and the IATA Safety Audit for Ground Operations (ISAGO).
IOSA assesses an airline’s operational management and control systems, while ISAGO examines the management systems and procedures used by ground-handling companies. Its scope includes passenger and baggage handling, aircraft ramp operations, load control, and cargo and mail handling.
The recognition is intended to support the use of internationally established audit standards and reduce duplication in compliance assessments. The programmes will complement, rather than replace, the Somali Civil Aviation Authority’s statutory safety oversight responsibilities.
The agreement was signed by Transport and Civil Aviation Minister Mohamed Farah Nuh, aviation authority director-general Ahmed Moallim Hassan, and IATA regional vice-president for Africa and the Middle East Kamil Alawadhi.
The arrangement forms part of IATA’s Focus Africa initiative, which identifies safety, infrastructure, connectivity, financial services, sustainability and workforce skills among the priorities for improving African aviation.
For airlines and ground-handling operators, acceptance of recognised audits may help streamline aspects of regulatory compliance. Its practical effect will depend on how the Somali regulator applies the agreement and the requirements individual operators must continue to meet.
Rebuilding aviation infrastructure
Somalia’s return to BSP comes amid broader efforts to restore national aviation functions following decades of institutional disruption.
In January 2023, Somalia resumed air traffic control services in high-altitude Class A airspace within the Mogadishu Flight Information Region after approximately three decades of disruption. The recovery involved improvements to aviation communications, navigation infrastructure and operational capacity.
The restoration of settlement services addresses a different part of the aviation system: the financial infrastructure connecting travel agents and airlines. Together with the recognition of international safety audits, it reflects efforts to strengthen the institutions and processes needed to support commercial air transport.
For Somalia’s travel businesses, the immediate priority will be translating the formal relaunch into reliable access to participating airlines, predictable settlement procedures and effective support for accredited agencies.
The BSP return alone does not establish how much additional ticket revenue will be generated, nor does it guarantee that all local agencies will be able to use the system. Those outcomes will depend on participation, implementation and the development of the wider aviation market.
Nevertheless, after 35 years without a domestic BSP arrangement, the relaunch restores an important link between Somalia’s travel trade and the global airline distribution system. The accompanying safety agreement adds a regulatory dimension to the effort, as the country seeks to strengthen both the commercial and operational foundations of its aviation industry.
Zanzibar is set for a significant expansion in air connectivity, with available airline seats forecast to increase by 33% over the next six months, according to new tourism intelligence released by the African Travel and Tourism Association (ATTA) at the international Buyer Forum, Essence of Africa, being held this week in Zanzibar between 20 and 22 October.
Analysis developed using Data Appeal’s Mabrian Travel Intelligence platform reveals strong growth in connectivity, changing international source markets and evolving visitor preferences.
Zanzibar’s inbound air capacity increased by 11% between October 2025 and October 2026, driven by international capacity growth of 11% and a particularly strong 26% increase in long-haul seats.
The momentum is expected to accelerate over the next six months, with domestic capacity forecast to rise 36% and international capacity 31% year-on-year.
The increase is accompanied by stronger forward flight bookings through global distribution systems (GDS), which are up 10% year-on-year for travel through March 2027.
Changing source markets
The Data Appeal’s Almaviva Group analysis highlights significant changes in Zanzibar’s international source markets, with expanding air connections from the Gulf, Europe and Russia.
The United Arab Emirates, Zanzibar’s fourth-largest international market by available flight seats, is forecast to record a 57% increase in inbound capacity over the next six months. Qatar is expected to grow by 17%, while Oman is forecast to more than double its available seats, rising 108%.
The figures reinforce the growing importance of Gulf aviation hubs in connecting Zanzibar with international travellers.
Established European markets also continue to demonstrate strong demand, with forward GDSs flight bookings from the UK increasing 51% year-on-year, followed by Germany (+14%) and France (+8%).
Russia has also recorded a notable increase in travel activity following the introduction of direct Moscow–Zanzibar services in July 2026. GDS flight bookings from Russia for travel through March 2027 have increased 98% year-on-year, while Zanzibar’s share of outbound flight searches from the Russian market has risen by approximately 8 percentage points.
The findings illustrate how Zanzibar’s international visitor markets are evolving as airline networks expand and travel patterns change.
Hotel rates fall despite growing visitor demand
While air connectivity and flight bookings are increasing, Zanzibar’s accommodation market is experiencing a more competitive pricing environment.
The Data Appeal – Almaviva Group analysis reveals that weighted average room rates advertised through online travel agencies fell approximately 18% year-on-year across the 12 months to October 2026, with declines recorded across all hotel categories.
The findings suggest increasing competition within the accommodation sector, potentially influenced by expanding international hotel brands and wider market conditions.
Zanzibar’s online hotel supply remains concentrated in the midscale segment, with 3-star properties accounting for 57%, followed by 4-star hotels at 28% and 5-star properties at 15%.
Beyond the beach: wellness, culture and independent travel gain ground
The Data Appeal’s Almaviva Group analysis also reveals how Zanzibar’s tourism appeal is evolving beyond its traditional sun-and-sea offering.
While beach experiences remain the leading driver of visitor interest, accounting for 23% of tourism-related related to social media mentions, active lifestyle experiences now represent 19%, followed by arts and culture at 16%.
Interest in family activities, wellness and gastronomy has also increased compared with the previous year.
The findings suggest opportunities for tourism businesses to diversify their products and attract visitors seeking experiences beyond the island’s beaches.
The visitor demand profile shows that couples remain Zanzibar’s largest traveller segment, accounting for 46% of reviewers.
Although hotels and resorts continue to account for more than 70% of reviewed stays, alternative accommodation including apartments, hostels and homestays is gradually gaining market share, suggesting growing demand for flexible and independent travel.
Strong destination reputation
Zanzibar continues to enjoy a strong reputation among international travellers, recording a Global Tourist Perception Index of 86 out of 100, supported by particularly high scores for Security (95) and Climate (90).
However, the findings also identify opportunities to strengthen the visitor experience. Zanzibar’s Tourism Product Index stands at 65/100, while its Hospitality Satisfaction Index is 74/100.
Satisfaction varies across accommodation categories, with 3-star properties scoring 69/100, compared with 77/100 for 5-star hotels and resorts.
Virginia Messina, CEO of ATTA, said:
“There’s no doubt, Zanzibar’s excellent reputation as a destination, exceptional natural environment and increasingly diverse visitor offering is driving airlines’ confidence to increase airline seats over the next six months and beyond.
Established European markets remain extremely important, while growing connections through the Gulf and other international gateways are creating opportunities to reach a broader range of travellers.
But growth in airline seats and bookings must also translate into sustainable commercial returns, investment in the visitor experience and benefits for local communities. These findings reinforce the importance of continued investment in hospitality standards, skills and tourism product development as Zanzibar expands its international reach.
“As Zanzibar continues to attract international investment and new hospitality brands, maintaining competitiveness while protecting the quality and value of its tourism product will be essential. The opportunity is to build on the destination’s popularity while encouraging visitors to stay longer, explore more and spend more widely within the local economy.”
Kenyan low-cost carrier Jambojet is exploring entry into South Sudan, opening a potential new market for the airline as it pursues regional expansion beyond its established domestic network.
The airline held talks with the South Sudan Civil Aviation Authority (SSCAA) in Nairobi on October 22, 2026, to discuss the possibility of operating services into the country. The regulator expressed its willingness to work with the carrier, subject to compliance with foreign-operator regulations and applicable safety requirements.
No route, flight frequency or launch date has been announced, and the discussions do not constitute approval to operate.
The talks come as Jambojet develops a longer-term network strategy aimed at expanding its reach beyond Kenya. The airline resumed daily flights between Nairobi and Entebbe on October 1, 2026, after suspending the Uganda service during the Covid-19 pandemic in 2020.
South Sudan would offer another potential regional market, with Nairobi already serving as an important aviation gateway for travel to Juba. Kenya Airways operates the Nairobi–Juba route, meaning any Jambojet entry would place the low-cost carrier in a market already served by an established regional airline.
The commercial opportunity will depend on the route’s passenger demand, operating costs, fares and the regulatory conditions governing market access.
Jambojet’s expansion plans are also tied to its fleet strategy. The airline operates De Havilland Canada Dash 8-400 turboprop aircraft, which are suited to short-haul services. In September 2026, Jambojet chief executive Karanja Ndegwa told Aviation Week that the airline was developing a 10-year network strategy that would inform future fleet and route decisions.
The carrier has previously outlined plans to increase its fleet from 11 aircraft towards 16 by 2029, supporting growth in its existing markets and potential entry into additional regional destinations.
For the travel trade, a Jambojet service to Juba could introduce another option for passengers travelling between Kenya and South Sudan, depending on the route selected and the fares offered. Travel agents, corporate travel managers and tour operators would need confirmed schedules and booking availability before incorporating the service into their products.
The regulatory process remains the immediate hurdle. During the October meeting, the SSCAA discussed its Commercial Air Transport by Foreign Air Operator Regulations, 2026, which govern foreign airlines seeking to provide commercial services in South Sudan. The authority also outlined its traffic-rights framework and invited a Jambojet delegation to Juba for further discussions.
The next steps will therefore involve regulatory engagement and the fulfilment of applicable operational and safety requirements before any service can be confirmed.
For now, South Sudan remains a prospective destination in Jambojet’s regional expansion plans rather than an announced addition to its published network.
Kenya, Tanzania and Uganda are exploring a common tourist visa for the 2027 Africa Cup of Nations (AFCON), an initiative that could ease cross-border travel and create new business opportunities for airlines, travel agents, hotels and tour operators across East Africa.
The proposal comes as the three countries report rising international visitor numbers and tourism earnings, strengthening the commercial case for marketing them as a connected destination rather than competing national markets.
Combined, Kenya, Tanzania and Uganda recorded approximately 6.63 million international tourist arrivals in 2025, generating about US$9.9 billion in tourism earnings, based on their respective national statistics. The figures cover different national reporting systems and should not be interpreted as a count of unique travellers across the region.
Kenya recorded approximately 2.7 million international arrivals and tourism earnings of about Sh500 billion in 2025. Tanzania received 2.29 million international visitors, generating US$4.41 billion, while Uganda recorded 1.64 million arrivals and tourism receipts of US$1.62 billion.
The proposed visa was endorsed by Ugandan President Yoweri Museveni during a meeting with the country’s AFCON Local Organising Committee in July 2026. The proposal envisages a four-month arrangement allowing eligible football supporters, tourists, officials and participating teams to travel between the three host countries without obtaining separate entry permits for each.
Museveni directed officials to begin discussions with Kenya and Tanzania. However, the endorsement is not a final tripartite agreement, and the proposed visa’s fee, eligibility rules, application process and operational dates have yet to be confirmed.
The timing is significant. AFCON 2027 is scheduled to run from June 19 to July 17, 2027, giving the tournament a defined window around which tourism businesses can develop regional travel products.
Three tourism markets, one regional opportunity
The scale of the three markets offers a useful starting point for assessing the opportunity.
Kenya’s international arrivals increased from approximately 2.47 million in 2024 to 2.7 million in 2025, a rise of about 9 per cent. Tourism earnings increased from Sh452.2 billion to approximately Sh500 billion over the same period.
Tanzania’s international arrivals rose 7.1 per cent, from 2.14 million in 2024 to 2.29 million in 2025. Tourism earnings grew 13 per cent, from US$3.90 billion to US$4.41 billion.
Uganda recorded 1.64 million international arrivals in 2025, up from 1.37 million in 2024, representing growth of approximately 19.7 per cent. Tourism receipts increased to US$1.62 billion from US$1.28 billion in 2024.
These figures point to three substantial tourism economies with complementary products: Kenya’s wildlife and coastal circuits, Tanzania’s safari and Zanzibar markets, and Uganda’s gorilla trekking, wildlife and cultural experiences.
For the travel trade, the commercial question is whether the visa can help turn these separate products into itineraries that generate additional nights, bookings and spending across more than one country.
A visitor attending a match in Nairobi, for example, could extend the trip to a Kenyan safari or the coast before travelling to Tanzania or Uganda. Such an itinerary would create opportunities for travel agents to combine international air tickets, regional flights, accommodation, transfers, park visits and guided excursions into a single sale.
However, these are potential business opportunities, not confirmed projections of additional arrivals or revenue. The actual return will depend on the visa’s final terms, transport connections, accommodation availability and the extent to which visitors choose to travel beyond the tournament venues.
The existing regional visa leaves Tanzania outside the arrangement
East Africa already has a common tourist visa covering Kenya, Uganda and Rwanda. The existing East Africa Tourist Visa costs US$100 and allows eligible visitors multiple entries into the participating countries for 90 days.
Tanzania is not part of that arrangement, making its inclusion in the proposed AFCON framework a significant policy change if the three governments reach an agreement.
The proposed four-month visa should not be confused with the existing 90-day product. Its price, validity and entry conditions remain unconfirmed, and the current visa’s terms cannot automatically be applied to it.
For travel companies, a clearly defined common visa could reduce uncertainty when quoting multi-country holidays. It could also simplify the explanation of entry requirements for international clients, although passport, immigration and other applicable conditions would still need to be observed.
The policy challenge is to ensure that the arrangement works across three national immigration systems without creating confusion over fees, permitted stays, border controls and the treatment of visitors entering or leaving the region more than once.
Regional tourism strategy sets a longer-term ambition
The visa proposal is part of a wider effort to strengthen East Africa’s position in the international tourism market.
On October 15, 2026, tourism ministers from the East African Community adopted a ten-year tourism marketing strategy covering 2027 to 2036. The framework promotes the region as a single destination under the brand Visit East Africa: Feel the Vibe, with priorities including digital marketing, cross-border packages, improved tourism statistics and progress towards a single tourist visa.
The strategy gives the AFCON initiative a longer-term context. If the visa and joint marketing arrangements are implemented effectively, the tournament could help establish regional itineraries that continue to be sold after the final whistle.
The EAC has also urged member states to improve tourism establishment classification ahead of the tournament, highlighting accommodation standards and service quality as important parts of the visitor experience. Uganda is scheduled to host the fourth EAC Regional Tourism Expo alongside the Pearl of Africa Tourism Expo in May 2027, incorporating AFCON promotion and multi-country tourism packages.
For tourism businesses, this creates a potential route from event-driven promotion to sustained regional sales. But marketing a destination jointly will only be commercially effective if travellers can move between countries conveniently and receive consistent service standards.
Visitor spending matters more than arrivals alone
The national earnings figures also show why the opportunity should be assessed in terms of visitor spending, not just the number of football supporters entering the region.
In Tanzania, tourism earnings increased 13 per cent in 2025, faster than the 7.1 per cent rise in international arrivals. The country reported average tourist expenditure of US$289 per person per night on the mainland, while Zanzibar recorded US$274. Uganda reported average tourist expenditure of US$986 per trip in 2025, up from US$933 in 2024, alongside an increase in average length of stay from 8.7 to 8.8 nights.
These figures use different measures and are not directly comparable. They nevertheless illustrate the commercial importance of encouraging visitors to stay longer, purchase additional experiences and distribute their spending among more tourism businesses.
For travel agents, this could favour packages that combine football with established attractions and clearly priced extensions, rather than itineraries built solely around match attendance. The opportunity will also depend on the availability of regional flights, reliable ground transport and accommodation at the right price points.
The three governments will need to publish the visa rules early enough for operators to price and market their products with confidence. Until then, businesses should avoid presenting the proposed visa as an available service or promising clients unrestricted travel across all three countries.
Implementation will determine the economic return
The proposed visa does not, by itself, guarantee an increase in tourism earnings. Its effectiveness will depend on how quickly the governments settle the technical and administrative details and whether the arrangement is integrated with the wider preparations for AFCON.
The private sector will also need reliable information on match schedules, accommodation capacity, transport links, entry conditions and the availability of regional tourism products. Without these, travel businesses may find it difficult to convert international interest in the tournament into confirmed multi-country bookings.
The stakes extend beyond the month-long competition. Kenya, Tanzania and Uganda collectively generated about US$9.9 billion in tourism earnings in 2025, according to their national figures. A more connected regional market could help the three countries sell longer journeys and broaden the distribution of visitor spending, although the size of any additional revenue remains unknown.
For now, the proposed common visa remains a policy initiative rather than an operational travel product. Its significance will ultimately be measured not by the announcement itself, but by whether it makes cross-border travel easier and creates lasting commercial value for East Africa’s tourism industry.